Stratford-upon-Avon
13 The Courtyard
Timothy's Bridge Road
Stratford-Upon-Avon
Warwickshire CV37 9NP


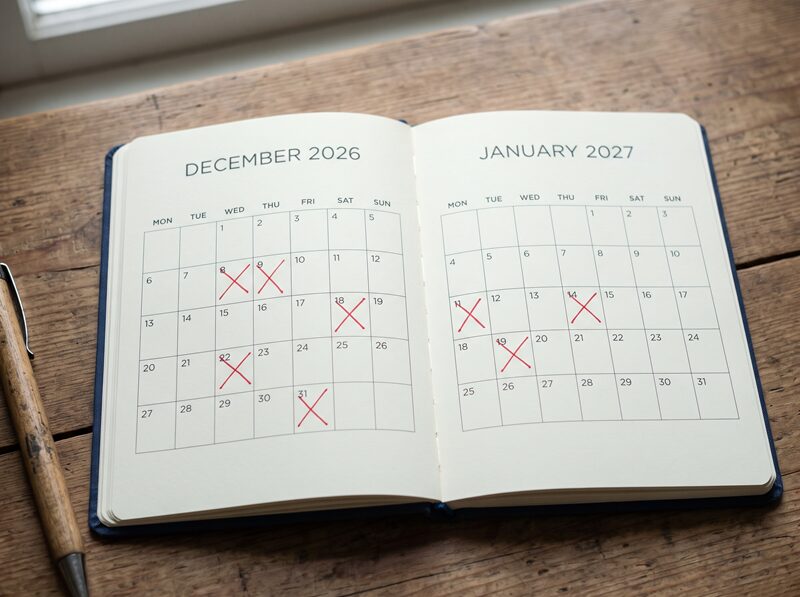
December 2026
1 December 2026 – Due date for Corporation Tax payable by companies with an accounting period ended 28 February 2026, unless the company is required to pay Corporation Tax by instalments.
7 December 2026 – VAT returns and payments are normally due for VAT accounting periods ended 31 October 2026, unless an alternative deadline applies, for example under the Annual Accounting Scheme.
19 December 2026 – PAYE and National Insurance deductions for the month ended 5 December 2026 must normally reach HMRC by this date where payment is made by post. As 19 December falls on a Saturday, postal payments should reach HMRC by Friday 18 December. Where payment is made electronically, the normal deadline is 22 December 2026.
19 December 2026 – Filing deadline for the CIS300 monthly return for the month ended 5 December 2026.
19 December 2026 – CIS tax deducted for the month ended 5 December 2026 must normally reach HMRC by this date if payment is made by post. As 19 December falls on a Saturday, postal payments should reach HMRC by Friday 18 December. Where payment is made electronically, the normal deadline is 22 December 2026.
30 December 2026 – Deadline for filing the 2025-26 Self-Assessment tax return online where an individual wants HMRC to collect a Self-Assessment liability of less than £3,000 through their PAYE tax code, subject to HMRC's normal conditions.
31 December 2026 – Companies with an accounting period ended 31 December 2025 must normally submit their Corporation Tax return to HMRC by this date.
31 December 2026 – Private companies with an accounting period ended 31 March 2026 will normally need to file their accounts at Companies House by this date. Different deadlines can apply to a company's first accounts or where the accounting reference date has been changed.
January 2027
1 January 2027 – Due date for Corporation Tax payable by companies with an accounting period ended 31 March 2026, unless the company is required to pay Corporation Tax by instalments. As 1 January is a bank holiday, companies should arrange payment in advance to ensure that HMRC receives cleared funds on time.
7 January 2027 – VAT returns and payments are normally due for VAT accounting periods ended 30 November 2026, unless an alternative deadline applies, for example under the Annual Accounting Scheme.
14 January 2027 – Deadline for submitting CT61 returns and paying Income Tax deducted from relevant payments, including certain interest payments made by companies, for the quarter ended 31 December 2026.
19 January 2027 – PAYE and National Insurance deductions for the month ended 5 January 2027 must reach HMRC by this date where payment is made by post. Where payment is made electronically, the normal deadline is 22 January 2027.
19 January 2027 – Filing deadline for the CIS300 monthly return for the month ended 5 January 2027.
19 January 2027 – CIS tax deducted for the month ended 5 January 2027 must reach HMRC by this date if payment is made by post. Where payment is made electronically, the normal deadline is 22 January 2027.
31 January 2027 – Deadline for submitting online Self-Assessment tax returns for the tax year ended 5 April 2026. As this date falls on a Sunday, taxpayers should allow sufficient time to complete and submit their returns.
31 January 2027 – Due date for payment of any outstanding Self-Assessment Income Tax and Class 4 National Insurance liabilities for 2025-26, together with the first payment on account for 2026-27 where applicable. Taxpayers should ensure that payments reach HMRC by the deadline.
31 January 2027 – Companies with an accounting period ended 31 January 2026 must normally submit their Corporation Tax return to HMRC by this date.
31 January 2027 – Private companies with an accounting period ended 30 April 2026 will normally need to file their accounts at Companies House by this date. Different deadlines can apply to a company's first accounts or where the accounting reference date has been changed.
Other deadlines to remember
Capital Gains Tax on most disposals of UK residential property must normally be reported and paid within 60 days of completion. The actual deadline therefore depends upon the completion date rather than being a fixed monthly diary date.
Employers should also remember that Full Payment Submissions under PAYE Real Time Information are normally required on or before the date employees are paid. Special reporting arrangements may apply where employees are paid earlier than usual because of Christmas or New Year holidays.
Companies House confirmation statements must normally be filed within 14 days of the end of the company's review period. The deadline depends upon the company's individual confirmation statement date rather than its accounting year end.
Making Tax Digital for Income Tax requires quarterly updates from individuals within the new reporting regime. The next standard quarterly update deadline for the 2026-27 tax year is 7 February 2027 for taxpayers using the tax-year reporting periods. Different dates can apply where calendar quarters are used.
Corporation Tax payment and filing deadlines are not the same. Most companies must pay Corporation Tax nine months and one day after the end of their accounting period, while the Corporation Tax return is normally due 12 months after the accounting period ends. Larger companies may be required to make quarterly instalment payments.
Grenfell James Technology Adoption Index
How does your business perform against others adopting financial tech? Find out with our interactive diagnostic:
1.
How does your business receive invoices?
A)
Invoices are mainly received in paper form
B)
Invoices are mainly received by email
C)
Invoices are emailed then automatically forwarded to a designated mailbox
2.
How are purchase invoices processed?
A)
Invoices are entered manually
B)
Invoices are attached to manually raised invoices
C)
Automated software (e.g. ReceiptBank, 1Tap, HubDoc etc) collates invoices
3.
How are accounts processed?
A)
Using Excel/paper-based
B)
Using Computer-based, offline software
C)
Using cloud-based accountancy software
4.
How often is business data revised?
A)
Data is updated annually
B)
Data is updated quarterly
C)
Data is updated monthly or more often
5.
How is banking updated for your business?
A)
Banking is updated manually
B)
Banking is updated by imports
C)
Banking is updated via a live feed
6.
How are bank payments made?
A)
Bank payments are manual
B)
Bank payments are made using bulk imports
C)
Bank payments are made directly via accounting software
7.
How are bank receipts reconciled?
A)
Receipts are chased and reconciled manually
B)
Receipts are chased and reconciled automatically
C)
A third-party platform is used to chase debts and collect fees
8.
How often are management reports produced?
A)
No reports are provided
B)
Reports are provided but often too late to be valuable
C)
Reports are automated with real-time information
Score 8-12:
Curious Exploration
Your financial technology phase is Curious Exploration
% of respondent businesses are in this phase too.
Switching accountancy systems may seem like an upheaval, but can be much more straightforward than most businesses imagine. From talking to our clients, they have found moving from paper invoicing and desktop-based accounting software to the cloud and apps quickly makes the transition process a worthwhile investment of time. Digital accounting solutions bring in streamlined processes, up-to-date business data and greater confidence in the accuracy of information when making financial decisions.
Grenfell James works with your team to fully assess the needs of your business and minimise the impact of any transitions for solutions we recommend.
Score 13-19:
Measured Discovery
Your financial technology phase is Measured Discovery
% of respondent businesses are in this phase too.
Once cloud accountancy software is in place, there’s still plenty of scope to improve your accountancy processes and make sure your business is maximising the benefits of adopting a digital accounting solution. Grenfell James assesses each business to understand how any implemented solutions are being used, identify areas for improvement and the needs of the business overall to support your business goals and achieve success.
Our team of experts can discuss a range of time-saving automation and get different apps and cloud-based solutions talking to create and manage a digital accountancy eco-system to help your business grow.
Score 20-24:
Bold Innovation
Your financial technology phase is Bold Innovation
% of respondent businesses are in this phase too.
You know the benefits of accounting technology and the impact it can have on your business goals. If you want to take it a step further, our team can conduct a systematic review of your processes, apps and business goals to ensure your digital accountancy ecosystem is keeping pace with the changing needs of a growing business.